

Keypoints:
- Kenya and Nigeria rank highest in Africa for payment interoperability
• Fragmented payment systems continue to constrain African trade and remittances
• AfCFTA ambitions depend on faster and cheaper cross-border transactions
KENYA and Nigeria have emerged as Africa’s most interoperable cross-border payments markets, but a new global index suggests the continent remains among the world’s most fragmented regions for moving money across borders, threatening efforts to boost intra-African trade.
The findings come from the inaugural Cross-Border Payments Interoperability Index, published by Singapore-based payments infrastructure provider Thunes in partnership with UK technology analyst firm Juniper Research. The study assessed 50 countries worldwide using indicators including digital infrastructure, financial inclusion, economic health, cross-border connectivity and market readiness.
Kenya ranked first in Africa and 36th globally with a score of 4.2 out of 10, while Nigeria placed second on the continent and 41st worldwide. Both countries outperformed larger African economies, reflecting years of investment in digital financial infrastructure, mobile money adoption, fintech innovation and payment modernisation. South Africa, Ghana and Senegal completed Africa’s top five.
Africa’s top-ranked payment markets
| African Rank | Country |
| 1 | Kenya |
| 2 | Nigeria |
| 3 | South Africa |
| 4 | Ghana |
| 5 | Senegal |
Why the rankings matter
The rankings arrive as African governments seek to accelerate economic integration through the African Continental Free Trade Area (AfCFTA), which aims to create a single market spanning more than 1.4 billion people.
While Kenya and Nigeria lead Africa’s rankings, the report’s most important finding is that the continent’s digital payments revolution remains largely confined within national borders. Consumers can transfer funds instantly at home, but businesses and households still face delays, high costs and regulatory hurdles when moving money across African markets. That disconnect threatens to limit AfCFTA’s economic potential and slows progress towards a truly unified continental market.
Domestic innovation stops at the border
The report identifies what researchers describe as an ‘interoperability gap’ between domestic payment innovation and international payment connectivity.
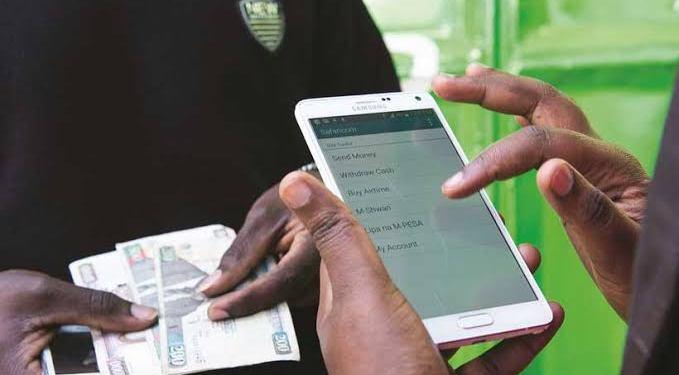
Across Africa, fintech companies and mobile money operators have transformed financial inclusion over the past decade. Kenya’s mobile money ecosystem and Nigeria’s expanding fintech sector are often cited among the world’s most successful digital finance models. Their success reflects a broader trend in which Africa’s fintech ecosystem is becoming a global innovation hub, particularly in digital payments and financial inclusion.
Yet these innovations have not produced seamless African cross-border payments.
Businesses trading across African borders frequently encounter multiple intermediaries, currency conversion costs and lengthy settlement processes. In many cases, transactions still pass through correspondent banking networks outside Africa before reaching their destination. These challenges mirror concerns raised by businesses across the continent, where payment fragmentation continues to slow regional trade despite AfCFTA ambitions.
The challenge extends beyond convenience. According to World Bank data, sending remittances to Sub-Saharan Africa costs around 7 percent on average, more than double the UN Sustainable Development Goal target of 3 percent. Remittances remain a vital source of household income across many African economies, making transaction costs a significant development issue.
The result is higher transaction costs for exporters, importers, remittance recipients and enterprises seeking access to regional markets.
AfCFTA faces a payments challenge
The findings highlight one of the least discussed obstacles to AfCFTA implementation.
Reducing tariffs and simplifying customs procedures may facilitate trade, but commerce cannot flow efficiently if payments remain slow and expensive. A company may be able to sell goods across borders under AfCFTA rules, yet still face difficulties receiving payment quickly and affordably.
To address this challenge, African policymakers have launched the Pan-African Payment and Settlement System (PAPSS), which seeks to enable cross-border transactions in local currencies while reducing reliance on foreign intermediary banks.
PAPSS has expanded steadily across participating African markets and is increasingly viewed by policymakers and central banks as a critical component of AfCFTA implementation. However, adoption remains uneven, and many national payment systems continue to operate independently.
For policymakers, the report serves as a reminder that payment infrastructure may be as important to regional integration as roads, ports and telecommunications networks.
Europe shows the benefits of interoperability
The report found that Europe dominates global interoperability rankings.
Sixteen of the world’s top 20 markets are located in Europe, benefiting from decades of regulatory coordination and integrated payment systems. Europe’s success has been driven in part by the Single Euro Payments Area (SEPA), which enables seamless transfers across participating countries and significantly reduces friction in cross-border transactions.
Denmark topped the global ranking, followed by Singapore and Norway.
The comparison highlights the distance Africa still needs to travel if it is to build a truly integrated digital economy.
Stablecoins reflect demand for alternatives
The study also points to changing user behaviour.
Nearly half of global users now prefer mobile wallets and payment applications for international transfers instead of traditional banking channels.
At the same time, stablecoins are emerging as an alternative for cross-border settlements. Their growing popularity reflects frustration with existing payment rails and demand for faster, cheaper international transactions.
In parts of Africa, businesses and consumers are increasingly experimenting with stablecoin-based transfers to avoid delays and costs associated with traditional cross-border payment systems.
However, regulators across Africa remain divided over how digital assets and stablecoins should be supervised, creating uncertainty around their long-term role in the continent’s financial system.
While regulatory questions remain unresolved, the trend underscores the market’s search for solutions to interoperability challenges.
The next stage of Africa’s integration
The rankings demonstrate that Africa has built some of the world’s most innovative domestic payment ecosystems.
Kenya’s leadership and Nigeria’s strong performance show that African markets can compete globally in digital financial services. Yet the report suggests the continent’s next challenge will be connecting these national systems into a seamless regional network.
Most African cross-border payments still rely heavily on infrastructure and correspondent banking relationships located outside the continent. That dependence increases costs, slows settlements and limits financial sovereignty. Initiatives such as PAPSS are increasingly viewed as a cornerstone of Africa’s emerging trade architecture, with Afreximbank positioning the platform as a key driver of digital trade integration across AfCFTA markets.
For a continent seeking to boost intra-African trade and reduce dependence on external financial infrastructure, interoperability may become one of the most important economic reforms of the next decade.
For AfCFTA to realise its full potential, moving money across African borders may need to become as simple as sending funds within a single country.
The rankings show Africa has already solved much of the domestic payments challenge. The next task is ensuring those systems can communicate across borders. Until that happens, the continent’s ambition of creating a single African market will remain constrained by the very payment barriers it seeks to dismantle.